


helen89/iStock Editorial via Getty Images
Overview
Founded in 1832, WSFS Financial (NASDAQ:WSFS) is the largest independent bank & trust company HQ in the Delaware – Greater Philadelphia region. Including the acquisition of Bryn Mawr Trust, on a Pro-forma basis, the bank has a deposit franchise of $17.3 billion, leapfrogging Santander (NYSE:SAN) to become the 7th largest franchise in the Phila-Camden-Wilmington area. WSFS has a regional presence in commercial, retail, and mortgage underwriting while maintaining a national presence in wealth management, cash connect, and NewLane equipment leasing.
WSFS has actively engaged in acquisitions to build up scale. As we mentioned in our article on Meridian Bank (NASDAQ:MRBK), Greater Philadelphia’s banking market is fragmented and has been consolidating over the years. WSFS, an active participant in mergers and acquisitions, has engaged in the following transactions since the GFC:
- 2014: Acquisition of First Wyoming Financial – The in-market acquisition bolsters WSFS’s presence in Kent county and strengthens its position as the leading independent community bank in Delaware.
- 2015: Acquisition of Alliance Bancorp & Penn Liberty – the acquisition of Alliance Bancorp allows WSFS to expand coverage in South PA and complements WSFS’s existing branch network; the acquisition of Penn Liberty complements WSFS’s existing network to bolster the presence.
- 2016: Acquisition of Powdermill Financial & West Capital – the acquisition of Powdermill continues to expand WSFS’s ability to serve HNW clients and adds wealth management capabilities; the acquisition of West Capital underscores the bank’s decision to expand the wealth management offerings to continue to drive fee income.
- 2019: Acquisition of Beneficial Bancorp – acquisition of Beneficial allows WSFS to become a top-ranked depository institution by market share and consolidates ~25% branch infrastructure; gaining scale rationalizes technological investments, which will continue to drive further efficiency over time.
- 2022: Acquisition of BMT – continues to build scale in the local market and adds fee generation capabilities while consolidating branches while eliminating costs.
After reviewing the list of acquisitions, the bank’s strategy has become clear – building a leading franchise in Greater Philadelphia market via acquisitions. WSFS will continue to engage in acquisitions to gain market share in the fragmented market. As noted in the chart below, there are considerable opportunities in the Greater Philadelphia market. Univest (NASDAQ:UVSP), Fulton (NASDAQ:FULT), Republic First (NASDAQ:FRBK), and Firstrust can be potential targets for the next deal.
Q4 IR Deck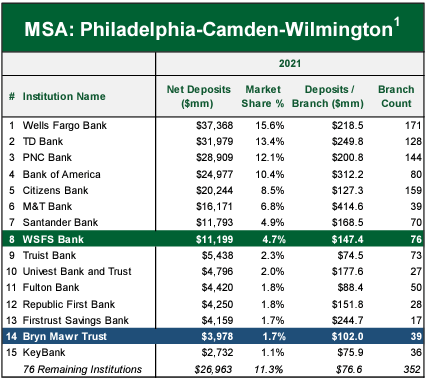
In reviewing the Q4 IR deck for investor guidance, the management team expects to achieve healthy mid-to-single digit ex. Residential mortgage growth; mid-single-digit fee revenues growth while maintaining a fee-to-income ratio at ~30%; efficiency ratio is expected to decrease, and the bank expects to drive Q4 2022 efficiency ratio to high 50s.
With the scale that the bank expects to achieve, WSFS has been investing in technology to drive efficiency improvement. The bank is implementing salesforce for improved customer cross-sell opportunities; WSFS is in the process of redesigning the account opening process and delivering a true omnichannel experience to reduce processing requirements; lastly, the bank expects to invest $15 mm in AML and fraud detection, incorporating robotic processing automation to minimize manual turnaround time.
Review of Operations
From a profitability perspective, although both ROA and ROE have been sporadic, both matrices have generally been improving over time.
The credit quality of the loan portfolio has been solid. Given the diversification of the loan portfolio, the bank has maintained good credit quality and performed well during COVID 19 period.
The bank has continued to improve upon its efficiency ratio, and as indicated in the 2022 outlook, the efficiency ratio should improve, benefiting from technological investments over time.
Cap IQ, 10-K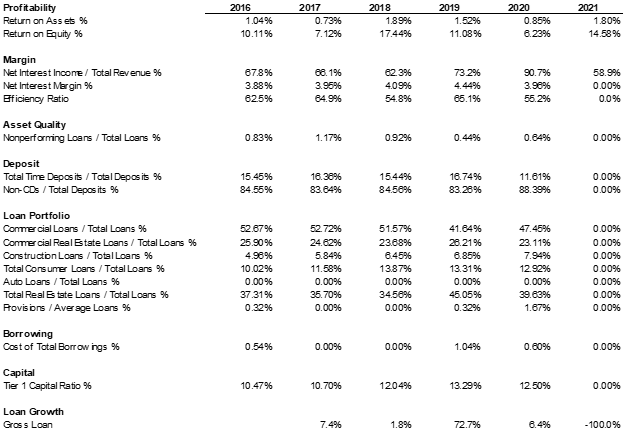
Valuation
The bank is priced at 1.8x P/TBV and 9.3x P/E. With the expectation of mid-single-digit loan growth and fee income growth, the bank is priced attractively on an earning’s multiple. Mortgage fee generation is only a tiny portion of the fee income for the bank, and given Cash Connect has been consistently growing at double digits per year, fee income from Cash Connect should be enough to compensate for a decrease in mortgage origination fees.
Cap IQ, 10-K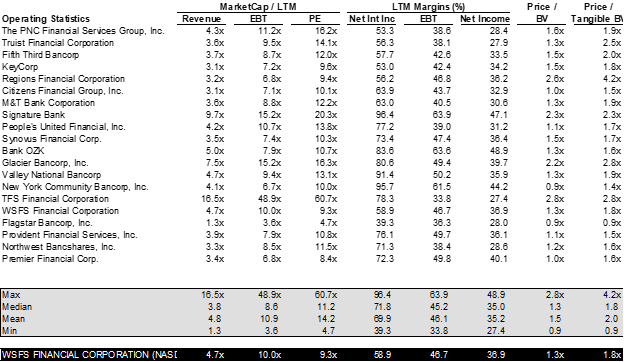
Risk/Reward
From a risk perspective, integration of BMT poses some risks. Also, larger-scale competitors can leverage the same acquisition strategy to build up scale within the Philadelphia market, thus driving up the purchase price for high-quality assets.
From a reward perspective, the bank is well-positioned in a rising interest rate environment. The bank’s solid fee generation capabilities will continue to earn returns above what other banks can produce. Over the long term, we expect the technology investment to continue to drive down operating expenses and streamline workflow, lowering overhead over time.
Conclusion
To sum up, WSFS is a leading independent bank in the Greater Philadelphia market. We continue to expect the bank to be active in acquiring assets and fold them into the existing structure. Priced at ~9x P/E with the mid-single-digit loan and fee income growth, investors have an attractive risk/reward opportunity. The bank has consistently repurchased stocks over time, and the board has suspended buyback because of the acquisition of BMT. Future buyback can be another driver for share price going forward.

